Good News and Bad News on Speed of Stock Price Adjustment in Thailand
Keywords:
Speed of stock price adjustment, Dividend announcement, Partial price adjustment, Event studyAbstract
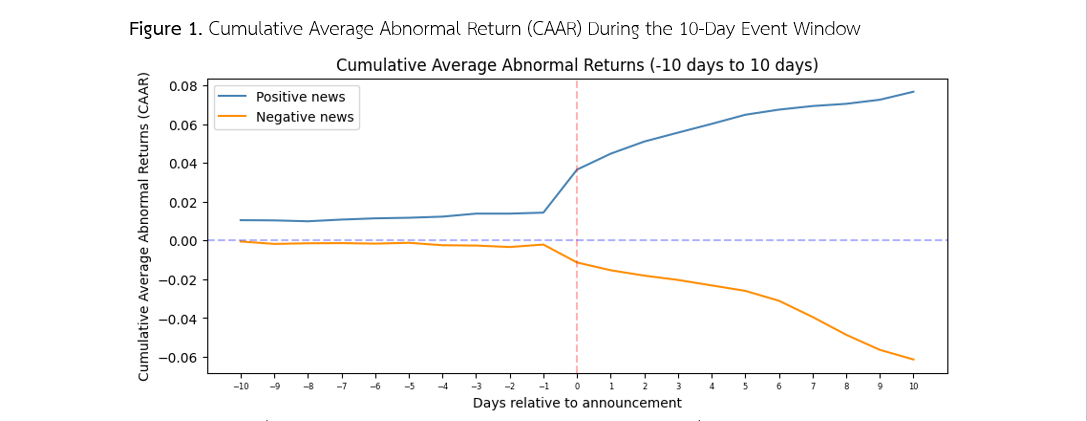
This study examines the speed of stock price adjustment towards corporate dividend announcement of listed companies in the Stock Exchange of Thailand (SET) and the Market for Alternative Investment (mai). The sample consists of 548 listed companies with 4,500 dividend announcement events during the period 2002–2022. This empirical research employs the event study methodology and the partial price adjustment model to measure the speed of stock price adjustment. Cumulative abnormal returns (CAR) are employed as a proxy for market reaction to new information. Multiple regression analysis using ordinary least squares (OLS) is employed to test the hypotheses. The results indicate that stock prices adjust gradually and do not fully incorporate new information immediately. In addition, the study finds an asymmetric adjustment speed between good news and bad news, where stock prices respond more slowly to bad news than to good news. Specifically, the variable for bad news shows a statistically significant negative relationship with the speed of adjustment at the 1% significance level across all tested periods (Dividend Announcement Day to Day 5 post-announcement), with coefficients ranging from -0.075 to -0.135. These findings provide important implications for investors and market regulators in developing investment strategies and disclosure policies. This finding is theoretically consistent with short-selling constraints and behavioral factors, particularly investors' tendency to hold losing stocks in their portfolios, which may contribute to the delayed price adjustment observed following negative news.
References
ณัฐพล มะลิซ้อน, อริชัย รักธรรม และทรงพร หาญสันติ. (2563). ผลกระทบจากการประกาศเงินปันผลต่อการเปลี่ยนแปลงราคาของหลักทรัพย์: กรณีศึกษา ตลาดหลักทรัพย์แห่งประเทศไทย. วารสารเกษตรศาสตร์ธุรกิจประยุกต์, 14(21), 15-32.
Barber, B. M., & Odean, T. (2013). The behavior of individual investors. In G. Constantinides, M. Harris, & R. Stulz (Eds.), Handbook of the Economics of Finance (Vol. 2, pp. 1533–1570). Elsevier.
Chan, W. S. (2003). Stock price reaction to news and no-news: Drift and reversal after headlines. Journal of Financial Economics, 70(2), 223-260.
Chiang, T. C., Nelling, E., & Tan, L. (2008). The speed of adjustment to information: Evidence from the Chinese stock market. International Review of Economics & Finance, 17(2), 216-229.
Damodaran, A. (1993). A simple measure of price adjustment coefficients. The Journal of Finance, 48(1), 387-400.
Diamond, D. W., & Verrecchia, R. E. (1987). Constraints on short-selling and asset price adjustment to private information. Journal of Financial Economics, 18(2), 277-311.
Epstein, L. G., & Schneider, M. (2008). Ambiguity, information quality, and asset pricing. The Journal of Finance, 63(1), 197-228.
Ersan, O., Simsir, S. A., Simsek, K. D., & Hasan, A. (2021). The speed of stock price adjustment to corporate announcements: Insights from Turkey. Emerging Markets Review, 47, Article 100778.
Fama, E. F., Fisher, L., Jensen, M. C., & Roll, R. (1969). The adjustment of stock prices to new information. International Economic Review, 10(1), 1-21.
Fama, E. F. (1970). Efficient capital markets: A review of theory and empirical work. The Journal of Finance, 25(2), 383-417.
Hirshleifer, D. A., Myers, J. N., Myers, L. A., & Teoh, S. H. (2008). Do individual investors cause post-earnings announcement drift? Direct evidence from personal trades. The Accounting Review, 83(6), 1521-1550.
Hong, H., Lim, T., & Stein, J. C. (2000). Bad news travels slowly: Size, analyst coverage, and the profitability of momentum strategies. The Journal of Finance, 55(1), 265-295.
Miller, M. H., & Rock, K. (1985). Dividend policy under asymmetric information. The Journal of Finance, 40(4), 1031–1051.
Srangtrakul, T., Ratchusanti, S., & Chingchayanurak, C. (2019). Speed of adjustment of securities’ prices in the SET 50 Index to macroeconomic information. Siam University Journal of Business Administration, 20(35), 41-54.
Weerawatsunthorn, K. (2012). An analysis of short sale and speed of price adjustment: evidence from the stock exchange of Thailand. (Master's thesis, Chulalongkorn University). Chula ETD.
Downloads
Published
How to Cite
Issue
Section
License
Copyright (c) 2026 Journal of Economics Maejo University

This work is licensed under a Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International License.